Solutions

Archive and retrieve communications securely with cloud-native speed.

Orchestrate real-time, compliant interactions across every channel.

Simplify and standardize trade and relationship documentation workflows.

Industries

Improve customer engagement across policy, billing, and claims.

Create and deliver personalized, compliant customer communications at scale.

Heighten citizen experience with digital transformation.

Improve customer engagement across utilities.

Resources

Browse popular market research, articles, videos, written guides and more in one convenient location.

Explore upcoming events, webinars, and customer experiences shaping the future of customer conversations.

Get the latest updates on Smart Communications, including product news, and industry recognition.

Company

Learn more about our company, our leadership and how were growing the team!

Analysts

Access analyst research, market reports, and industry recognitions featuring Smart Communications.

The Power of Integrated Insurance Solutions a Key Theme at Guidewire Connections 2021


By: Ruth Fisk, VP Insurance Marketing at Smart Communications

Earlier this month, the Smart Communications team gathered with insurance industry leaders at Guidewire Connections 2021. It was great to be able to meet in person (with precautions in place, of course) and learn from the people driving innovation for the industry. We were especially thrilled to celebrate 100 mutual customers with Guidewire!

As consumers increasingly prefer more personalized interactions and insurers navigate keeping up with the pace of change, the power of integrated insurance solutions is clearer than ever. Feeling inspired to dive into this topic a bit more, in this post we gather our three biggest takeaways from our time at the event.

Takeaway #1: The insurance industry is evolving and innovating.
In an earlier post, we discussed that the insurance industry is at an inflection point, where insurers need to take a more proactive approach to risk management. The combined trends of increasing customer expectations for personalized, real-time interactions, growing access to data and sophisticated technology and rising competition from insurtechs are forcing insurers to rethink how they manage risk and engage with customers.

This was a core theme at the show, and Mike Rosenbaum, CEO of Guidewire, highlighted the power of integrated insurance solutions – like Smart Communications and Guidewire – to enable insurers to engage customers, innovate and grow efficiently in this new era.

Takeaway #2: Maintaining the status quo will hamper success.
Companies across industries are being forced to challenge the status quo in an effort to respond to increasing customer demands, competition and more. No action is simply not an option – those that fail to innovate and evolve will be left behind.

Adopting a strategic approach to innovation and technology investments is possible, however. One of the most motivating sessions came from Andy Taylor, CEO of Gore, where he highlighted how a digital-first strategy helped the 180-year-old company transform 80% of its business in under two years. Accelerating technology replacements enabled the business to scale operations and become a high-performing national insurer.

Takeaway #3: There is an urgency to commit to innovation now.
Perhaps the biggest takeaway from Guidewire Connections? It’s critical to commit to innovation now.

Together with Kurt Markus of Mountain West Farm Bureau Mutual Insurance Company, we presented how we are working together to exceed customer expectations through a digital-first policy and claims strategy. The integrated insurance solutions of SmartCOMMTM and Guidewire Insurance Suite what used to take days and hours now only takes minutes.

Mountain West had decades-old processes and knew they needed to move to a digital-first approach and sophisticated technology. Previously, print was the only communication channel available, which led to challenges meeting consumer and agent expectations. With its new processes and technologies, however, Mountain West has scaled and automated personalized policy communications that also meet compliance requirements – without any heavy administration burdens.

The lesson? It’s important to commit to change now and with partners like Smart Communications and Guidewire, insurers will start realizing value.

—

Interactions between insurers and their customers have never been more important and the best way for companies to succeed is to prioritize digital-first, omnichannel customer experiences. Powerful integrated insurance solutions empower insurers to deepen customer relationships, drive loyalty and build amazing customer experiences.

In his keynote, Mike Rosenbaum indicated that the Guidewire ecosystem will deliver 100x more value to the insurance industry over time. We are so proud to be a part of this and to continue delivering value to our mutual customers. Together, our innovative cloud solutions enable smarter policyholder conversations across multiple channels and allow for meaningful interactions that simply aren’t possible via legacy systems and outdated processes.

—

To learn more about becoming a digital-first claims organization, check out our latest white paper where we discuss how to improve claims accuracy, reduce claims expenses and increase CSAT scores.

Omnichannel Insurance Solutions – the Next-Generation of Greatness


By: Ruth Fisk, VP of Insurance Marketing at Smart Communications

We are living in an always-on world – everything from ordering dinner, to opening a new bank account or filing an insurance claim can be done from a mobile device, in real time and when it suits the customer rather than the business. This is forcing the insurance industry specifically to rethink how they interact with their customers across a variety of channels and puts pressure on them to invest in omnichannel insurance solutions to effectively orchestrate interactive, two-way conversations as opposed to transactional, one-way communications.

The insurance industry has a long history – centuries, in fact – of adapting to change like this. In this post, we dive into how an omnichannel distribution model is helping leading insurers to deliver upon their guiding principles at the same time that customer needs evolve. We also provide a real-world example of an insurer doing this today.

Omnichannel Insurance Solutions for the Future

Times have changed and so too have insurers – yet their principal purposes remain the same, including:

  • Payments of Losses – ensuring insured individuals are less dependent on public assistance or relatives
  • Anxiety Mitigation – lets people know they are covered if a loss occurs
  • Support for Credit – aids in obtaining loans if insured
  • Accident Prevention – lives and property are saved


While insurers continue to focus on delivering these same important benefits to society, today’s modern insurer depends on new technologies and strategies – including advanced omnichannel insurance solutions – to meet the changing needs and expectations of their policyholders.

It’s no secret that the industry has seen more rapid change in the last 10 to 15 years than in the combined 350 years before, with today’s most meaningful contrast tied to how insurers deliver their products and services.

Today, insurers must effectively manage – or orchestrate – customer interactions to make them part of a continuous conversation rather than isolated, disjointed transactions. An effective omnichannel distribution model enables insurers to add digital channels to their print efforts, automate common customer interactions, effectively promote two-way conversations and more. This ensures that approved, compliant communications are delivered in real time and initiated when the customer demands it.

Wawanesa Insurance and the Power of a SMART Integration with Guidewire

This rapid evolution in the last few years has prompted industry leaders to build an ecosystem that brings together the best of breed solutions with pre-built code, accelerating the delivery of this combined functionality for today’s modern insurer. Leading insurers like Wawanesa Insurance want to focus on delivering value to their customers, not on the intricacies of integrating platforms. They rely on SMART partners to make this as seamless – and effective – as possible for their teams and their policyholders.

To address this, Guidewire, a leading technology platform provider for property and casualty insurance carriers, created their Ready for Guidewire accelerators.  Smart Communications has worked closely with Guidewire to develop more than a dozen of connectors available to InsuranceSuite on the Guidewire Marketplace.

Smart Communications is proud to provide the #1 Customer Conversations Platform that Guidewire customers count on to uniquely deliver personalized, omnichannel conversations – empowering them to succeed in today’s digital-focused, customer driven world.

Wawanesa leverages Smart Communications pure-cloud communications platform to deliver hyper-personalized, omnichannel experiences that reinforce the organization’s commitment to member centricity. Through this work, the organization has streamlined communications, enabled greater consistency and improved the customer experience to:

  • Provide a fast and simple way to share information with policyholders
  • Boost productivity
  • Reduce reliance on IT to perform all CCM related work


By investing in cloud-based solutions like the Smart Communications Conversation CloudTM, Wawanesa has lowered operational costs and improved the user experience, so they’re always ready to deliver leading-edge service.

“The Smart Communications claims release is a game changer by automating a time-consuming process and rationalizing an inventory of more than a thousand documents to ensure that we provide consistent, professional and accurate customer communications. Wawanesa is committed to continuing to invest, listen, and more importantly, focus on being a trusted partner.”   – Wawanesa Insurance

At Smart Communications, we are proud of the innovation we’re seeing across the insurance industry, both with leaders at insurance companies around the world and with our technology partners like Guidewire. Together, we’ll continue to chart a path toward excellence, driven by efficiency inside the organization and a top-notch experience for the policyholders that together, we support.

As we look forward to next month’s Guidewire Connections event in Las Vegas, we are ready to convince you to add more power to your Guidewire investments – and improve your customer communications strategy. More than 100 Guidewire customers across the globe trust Smart Communications to deliver SMARTER conversations across the complete customer lifecycle.  We’re ready to tell you why live! See you at the Smart Communications booth (P2) at #GuidewireConnections!

Taking a Proactive Approach to Risk Management in Insurance


By: Ruth Fisk, VP of Insurance Marketing at Smart Communications

Insurance exists to protect us – as individuals, as families and as businesses – and assist us when we need it most, after natural disasters, accidents, illness and more. When it comes to risk management in insurance however, the industry is at an inflection point. Today, insurers need to take a more proactive approach to risk prevention.

A convergence of several macro-level trends is forcing insurers to rethink how they manage risk and engage with customers. Those trends include:

  • Increasing customer expectations for personalized, real-time interactions
  • Growing access to data and sophisticated technology
  • Rising competition from up-and-coming insurtechs


For decades, insurers have used a reactive approach to business. If an event occurs, a customer will initiate a claim and the insurer will respond appropriately. Today however, insurance companies must evolve to become more proactive and minimize risks as much as possible.

In this post, we dive into why a more proactive approach is beneficial to risk management in insurance, how modern technology and new coverage models can be beneficial and why optimizing customer communications is integral to success.

Sharing Education Opportunities

A proactive approach to risk management in insurance begins with education. In the midst of hurricane season, for example, customers need to be better prepared from an insurance perspective. There are some customers that have probably been insured for decades but have never filed a claim. If insurers are providing helpful emergency preparedness advice up front, it ultimately creates a better experience for customers if they know what to do before disaster strikes.

We have also seen an increasing number of insurers sharing advice guides, which aim to steer customers to the kind of coverage they should have, their greatest areas of risk and more. Whether it’s preparing for storm season or advice for a young adult just starting out, there are countless areas where insurance companies can provide more education, such as:

  • How to protect property from further damage
  • Tips for preventing housefires
  • How to prepare a disaster plan
  • How to file a claim
  • Benefits of a connected home
  • Wellness tips, including nutrition, exercise and stress reduction


New Use-based Coverage Models

Many up-and-coming insurtechs are moving to newer service models that provide coverage on a need-only basis – think a “pay as you go” model. For example, Trov offers digital, in-app embedded insurance products while Slice provides usage-based insurance products anytime and anywhere.

By adopting new coverage models, insurers can meet customers where they are. With telematics, Artificial Intelligence (AI) and more, insurers not only reduce risk, but also enhance the overall customer experience. The industry has already started adopting some of these practices with programs like safe driving apps that leverage telematics and data to help drivers secure better rates. And with homes becoming “smarter,” insurers need to take advantage of the data and insights newer technologies provide. Hippo, for example, offers monitoring systems that protect against fire, water damage and theft.

A New Era of Customer Conversations

Today, anything consumers want is only a few taps or clicks away. And with the pandemic forcing many people to rely solely on digital to meet even basic needs, customers have higher expectations than ever.

Insurers are increasingly being measured by how well they know their customers – experiences must be tailored to the individual. Successful personalization efforts depend on great data – collecting it in a way that is frictionless for the customer, and then leveraging a robust customer communications platform that can put it to use. Moving to a cloud model and leveraging open APIs will support a more modern and proactive approach to risk management in insurance. This will allow data from core systems, third-party solutions and more to be incorporated into tailored, personalized customer conversations.

Ultimately, customers want to feel like a name, not a number. Insurers that provide customers with risk mitigation tips and strategies, plus tailored advice to prevent (and what to do in the event of) an accident or natural disaster, will be the ones to come out on top of the competition.

—

Smart Communications is thrilled to be a Platinum Sponsor of Guidewire Connections 2021. Please stop by our booth (P2 in the Partner Pavilion Pinyon Ballroom) to chat with us and learn more about how we empower insurers to deliver more personalized customer conversations. 

You can also catch us at our speaking session:

Mountain West Enriching Policyholder Experiences with Digital-First Strategies

Wednesday, Nov. 3, 2021

3:45pm – 4:30pm PST

Ironwood 1-2 

If you’d like to schedule a one-on-one meeting with one of our representatives, please contact us today.

How Financial Institutions Can Remove Friction from Data Collection for KYC and AML Compliance

 Financial institutions, especially those dealing with large deposits like wealth management firms, have a dilemma when it comes to compliance with Know Your Customer (KYC), Anti-Money Laundering (AML) data collection and other regulatory requirements. On the one hand, firms and their advisors must comply with these regulations – they are in no way optional. On the other hand, the rules can be cumbersome and add friction to key client touchpoints – like new account opening and onboarding – taking time and making the customer experience more frustrating.

The combination of heightened customer expectations around digital experiences, shifting demographics and intensifying competition from robo-advisors, means wealth management and other financial services firms face increasing pressure to make data collection for KYC as smooth and painless as possible.

Let’s look at actionable strategies for proactively managing the process of collecting information and backup documents for KYC in a way that ensures regulatory compliance while actually delivering a fast, easy customer experience.

Technology Integrations Overcome New Account Opening KYC Compliance Challenges

The trend of opening new accounts completely online had been on the rise for some time but was accelerated by the implications of the COVID-19 pandemic.

According to Deloitte, 63% of wealth management clients claim that online interfaces are a key component of satisfaction with their advisor’s firm.

And while this might be great news for consumers, it’s a massive headache for financial services firms that need to know exactly who these new applicants are. Running afoul of regulations because of not properly vetting applicants means more than just a slap on the wrist: financial firms have been fined $26 billion in sanctions for AML and KYC non-compliance since 2008.

The best way to avoid non-compliance during account opening, whether completely online or in-person, is to see data collection for KYC processes as a component in a technology ecosystem designed specifically to minimize compliance risks. By leveraging key integrations, wealth management, superannuation and other financial institutions can automate the process of assessing a potential new client’s risk of non-compliance.

Transforming Data Collection for KYC During Client Onboarding: From Static Forms to Dynamic Conversations

Often today the process of KYC data collection for identity and risk assessments starts with a static, non-fillable PDF form. Beyond the fact that they are tedious and time consuming, the problem with these forms is that the advisor or firm then needs to rekey in the information. This manual effort results in high rates of Not In Good Order (NIGO) rejections and a heavy lift on resources to manually correct information.

In addition, KYC regulations require a photo of government-issued ID, such as a passport. But investors don’t have the ability to effectively complete the data-capture process by simply leveraging their mobile device camera while completing onboarding documentation.

What financial services firms need is a solution that orchestrates digital customer communications, establishing two-way interactive conversations. If client information already exists in a CRM solution, why should the client need to enter it again? Instead, they can simply verify that the information is correct and update as necessary. Empower them to start and stop a digital interview on different devices as needed and enable collaboration by capturing information simultaneously from a spouse or other joint investor. The less time clients and financial advisors need to spend on data collection for KYC, the more time advisors have with them to build meaningful relationships.

More than 40% of wealth management firms already offer digital onboarding, and it is expected that nearly 70% will offer digital onboarding by 2022.  According to Gartner, 82% of wealth management firms are investing in client-facing technology in the next two years.

SmartIQTM, Smart Communication’s guided digital interview solution, uses the open APIs connected by the Conversation Cloud™ to automatically send data to third-party systems to validate client identity. The solution also easily integrates with other tools that specialize in connecting data and case management for KYC risk assessments, such as OneSpan and Pega.

A guided digital interview solution like SmartIQ changes the entire dynamic of client onboarding in financial services. Instead of the dreary process of filling out paperwork, advisors can transform onboarding into an enjoyable experience that sets the tone for the relationship early on. There’s a huge difference between an exciting conversation around how best to secure a client’s financial future, and “First name? Last name? Address?” Advisors should ask themselves, “which experience would clients return to and tell their friends about?”

Creating Powerful Personalized Experiences – One Client at a Time

At the end of the day, clients want to feel special, whether they are investing $10,000, $100,000 or more. They want to feel like they are receiving preferential treatment and can avoid common tasks that are perceived to be low value, like filling out paperwork. Unfortunately, static PDF forms send the opposite message. And while specific data points are necessary for KYC compliance, the approach to data collection can make or break a client’s experience.

SmartIQ enables wealth management and superannuation firms to avoid filling out information that already exists, but still capture the necessary data for KYC, AML and other compliance frameworks. The ability to do this from anywhere on any device makes discerning clients feel like a name, not a number. It shows that advisors care enough about the customer experience to invest in technology that makes their lives easier. That’s really the essence of personalization – meeting clients where they are with an experience they feel like was designed exclusively for them.

As we’ve seen, financial services firms can be proactive in removing the friction caused by KYC data collection while remaining fully compliant with regulations, both now and in the future – all while providing a personalized experience that high net worth individuals expect. With the right technology in place, wealth managers no longer have to choose between strict KYC compliance and a fantastic customer experience.

The New Rules of Digital Transformation Strategy


By: Neil Greathead, Chief Customer Officer at Smart Communications

Digital transformation strategies have been hot topics for quite some time, and most businesses have been making steady progress to achieve their digital goals. That is until the pandemic struck. Suddenly, plans became accelerated, and many businesses discovered just how much progress could be made in a short period of time with sustained focus and effort. As customer expectations continue to rise, enterprises around the world need to double down on these strategic digital efforts to ensure the end-to-end experience is better than ever.

In this post, we share exclusive insights into the new rules of digital transformation strategy, with help from Leroy McCarty, VP of Operations at Forrest T. Jones & Company, a leading Smart Communications customer. Forrest T. Jones leverages both SmartCOMMTM and SmartIQTM as the foundation for its organization-wide digital modernization journey – exceeding customer expectations at every step of their journey.

Rule 1: You must define a long-term vision rooted in meeting customer needs and expectations.

Creating and executing on a digital transformation strategy is a journey, and without a clear destination in mind, it’s easy to get off track. Take the time to clearly define what the digital future looks like for your organization, based on your customers’ needs and expectations.

“We had a vision for the future, for the modernization of really everything we did, and digitization was a key part of that strategy…we made sure that we were aligned with expectations of the customer for the journey that they expected to take.” – Leroy McCarty, Forrest T. Jones & Company

This requires listening carefully and keeping an open mind, as their feedback might be different from what you expect. You can also leverage industry research, like Smart Communications’ benchmark study, which makes it clear that:

  • 86% of consumers prefer digital technology over other forms of communications
  • 57% of consumers will abandon an interaction if a company has an inefficient process for collecting information
  • 63% of businesses think they are delivering excellent or very good communications, but only 51% of consumers agree


Rule 2: You must break down internal silos to create a truly customer-centered organization.

With your digital strategy in place, you can now focus on the “how”: what do you need to do to achieve that vision in the timeframe you’ve set for yourself? As you get to work, it’s important to think holistically. You need both your back-end and front-end processes and touchpoints in between working in harmony with each other to achieve your goals. The objective here is synergy: whatever technology you decide to implement for back-end data processing and integration handling should work seamlessly with a front-end experience that customers will love.

“Smart Communications has come in to help us with our digital strategy and to respond to the new expectations of the market, giving us the front-end and back-end to our entire lifecycle of an application.” – Leroy McCarty, Forrest T. Jones & Company

The best part? You don’t have to choose multiple vendors to follow this rule. It’s actually better if you don’t, because the simpler your digital transformation strategy is, the more likely you are to achieve it. That’s why organizations like Forrest T. Jones choose Smart Communications for both their cloud-based Customer Communications Management (CCM) and dynamic digital forms technologies. This one-two punch streamlines your approach and empowers you to achieve your vision faster.

Rule 3: Your digital transformation strategy must enable better omnichannel experiences at scale.

Consumers these days are practically swimming in a sea of digital devices. And whether it’s related to financial services, healthcare, insurance or other critical industries, consumers want to get things done from whatever device they happen to be holding at the time. Practical concerns like making sure customers only have to enter their information once (or even better, have forms pre-filled with the information you already have) are where the digital transformation rubber meets the road.

“Where SmartIQ has helped us tremendously is allowing us to take anything that we need to get from a customer and put it in front of them wherever they are, whatever time of day, whatever device they’re on, and help them do business with us.” – Leroy McCarty, Forrest T. Jones & Company

The challenge to getting this right is not just with one interaction in one place (say, your website) at one time, but everywhere a customer chooses to interact with you. Plus, customers should be able to initiate a digital interaction on one device, and pick up where they left off on another. Next-generation digital forms offer significant advantages over paper-based or static forms, creating an omnichannel experience that is personalized, collaborative and automated. Technologies like SmartIQ provide customers with fantastic experiences on the front-end while requiring minimal IT resources on the back-end – a win-win for everyone.

The Time for Digital Transformation is Now

Transformation can be daunting because there’s no time to waste in creating the best digital customer experience. Fortunately, as organizations like Forrest T. Jones & Company have learned, the right partner can make all the difference.

“We were fortunate in that we had a pretty clear vision for what we thought the future was going to hold, and so we aligned ourselves with Smart Communications to be able to deliver on that vision.” – Leroy McCarty, Forrest T. Jones & Company

To learn more about how Forrest T. Jones & Company use Smart Communications to transform their customer conversations, check out the video below.


Optimizing Member Engagement at Every Point of the Health Insurance Journey


By: John Zimmerer, VP Industry Marketing, Healthcare at Smart Communications

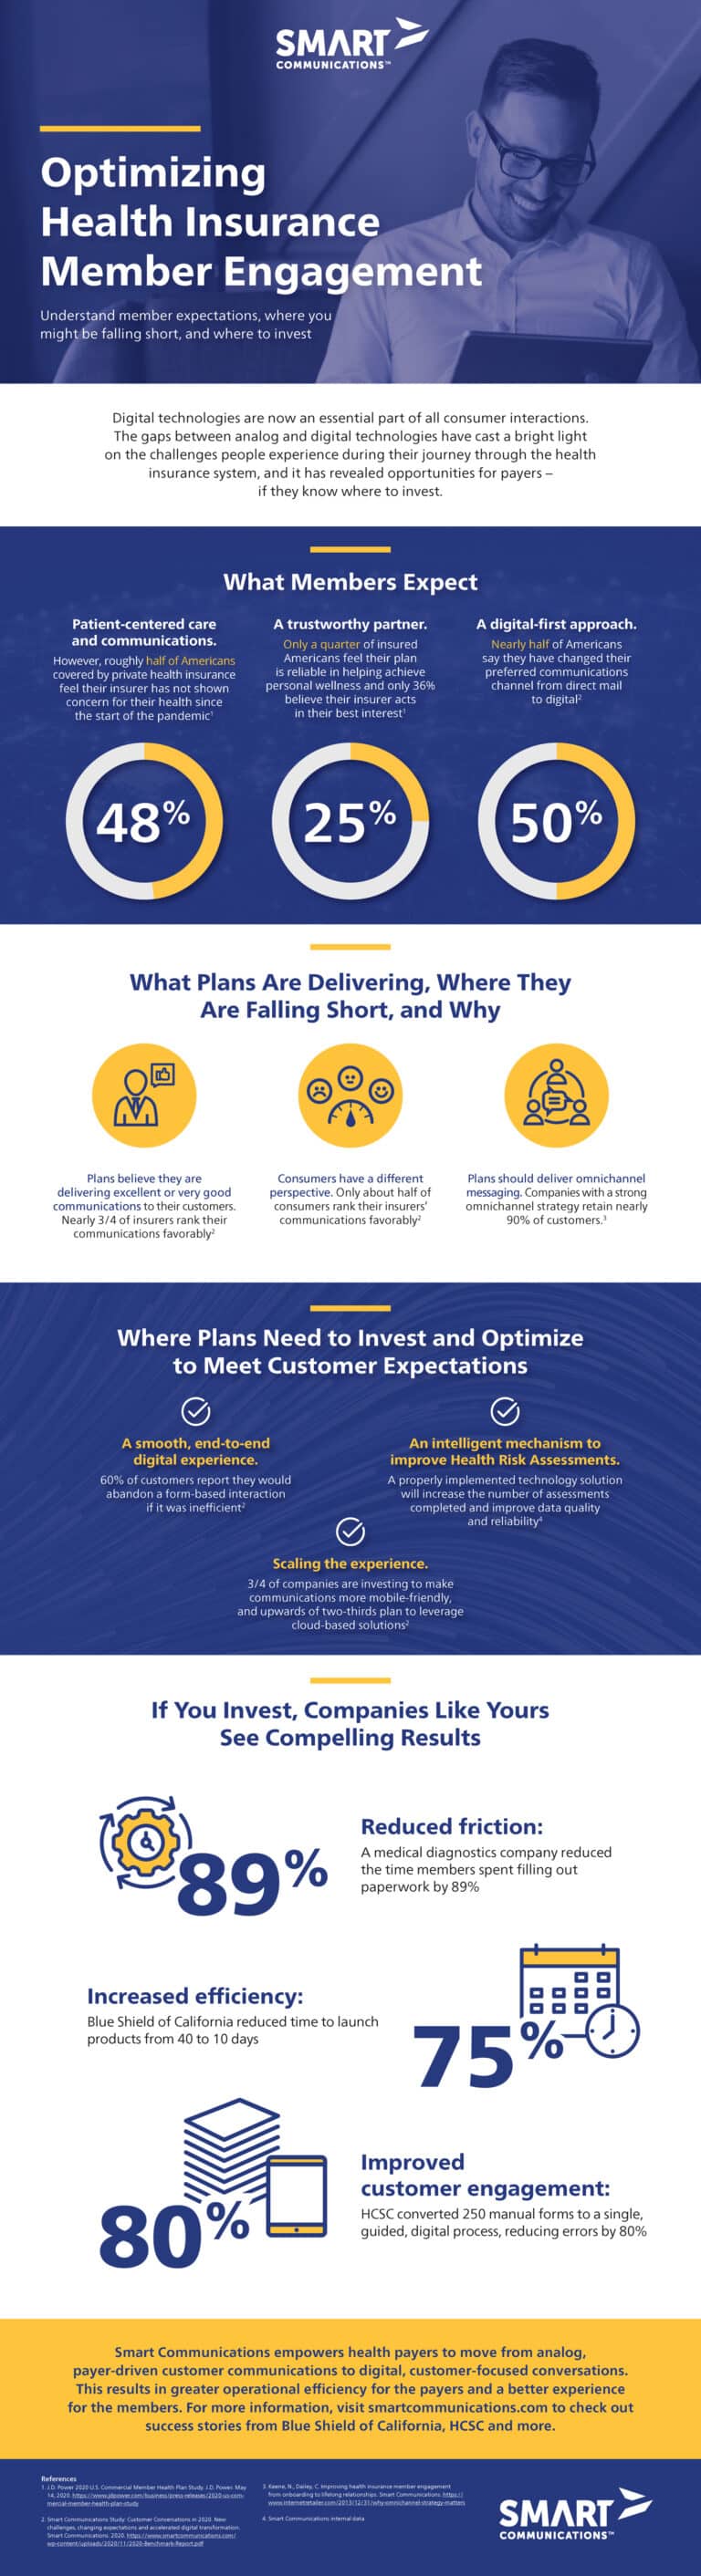
Many health insurers – roughly 75% — believe their member communications are excellent or very good. However, members have a different perspective, with only about half ranking their insurers’ communications favorably.

Unfortunately, health insurers all too often view member communications fine as-is. In today’s climate, however, where members expect a tailored, digital-first approach, insurers must better understand and meet these expectations to enhance the end-to-end member journey. This means optimizing every interaction, starting with enrollment and onboarding to managing the claims process and introducing care management initiatives.  For example, knowing that 60% of members would abandon an inefficient form-based process, a medical diagnostics company implemented a solution that cut the time members spent filling out paperwork by 89%.

In this infographic below, we highlight what members expect, where plans are falling short and where they should invest to succeed long-term. Keep reading to learn more:

To take a deeper dive into the member journey, check out our new white paper, Digital Enrollment and Onboarding for Health Insurance Plans. We explore every touchpoint of the enrollment process and identify key areas of optimization that will set your member experience apart from the competition.

Lessons Through a Lens: Pandemics Changing Communication in Insurance


By: Ruth Fisk, VP of Industry Marketing, Insurance at Smart Communications

More than 17 pandemics have plagued the world dating back as early as 430 B.C. Some are more well-known than others, but there is no doubt COVID-19 will be well remembered as a pandemic that changed the world. The 1918 Spanish Flu, the deadliest pandemic on record, and COVID-19 have a striking number of similarities. Just more than 100 years apart, each forced business to restrict operations, schools to close, stay at home orders to be enacted, masking and social distancing to become a must. The economic and social impact of each was devasting, forcing a shift in thinking about how we deliver products and services and – as importantly, how we communicate in new meaningful ways with the customers we serve.

Insurers too have been impacted by the outcomes of the pandemic, forcing them to readjust their business strategies so that they can better cater to the expectations of today’s consumers — especially during claims interactions where their customer retention and satisfaction rates are at the highest risk. There may be lessons insurers can glean from the pandemics to help them adjust to the next new normal. Let’s take a closer look.

Evolving the Way Products and Services are Delivered

Today’s “Hollywood” was born out of the 1918 pandemic, when 90% of movie theaters were shuttered. Adolph Zukor, co-founder of Paramount Pictures, had the vision to deliver full feature films through new channels, focused on the customer experience. Adolph purchased the closed theaters, built the movie empire, and transformed the movie industry. Similarly, insurance too will need to adapt to a new way of thinking by reevaluating the customer journey – every interaction can be a make-or-break moment in the retention strategy for that customer. It will not be enough to simply set up a digital front end, while still forcing your customer to engage in antiquated processes, e.g., filling out and returning a claim paper form.

EY reports “The COVID-19 pandemic is accelerating the transformational trends impacting the insurance sector and highlighting the need to take bolder actions in areas such as digital capability and effective engagement to address the customer’s needs post-pandemic.”

The insurance industry must rethink its business models to meet the expectations of policyholders. Consumers expect insurers to have the ability to have meaningful, two-way conversations whenever they need them to happen, across their preferred channels (mobile, web, human). Insurers must pivot in the way they deliver products and services; to do this, they should retool their communications platforms to have SMARTER conversations with their customers.

Technology Adoption Increases During Pandemics

Communications were difficult in 1918. Individuals relied solely on printed newspapers to receive updates on the pandemic. Businesses sought new and creative ways to reach customers. The 1918 pandemic dramatically changed the way we live and communicate today. One example – in-home telephones became a staple, helping individuals and households to feel less isolated and more connected.

Insurance companies can also learn from this lesson. The policyholder typically has little to no interaction with the insurer until a claim occurs and even then they often feel like communication is scarce, which makes them feel isolated during their greatest time of need. Best practices are now showing significant opportunities to improve customer satisfaction in claims if communications are approached as personalized, two-way conversations rather than broadcasting one-way messages that leave the insured feeling disconnected.

New Communications Methods Become Mainstream

As a result of the pandemics, we can now see the rapid adoption of essential technologies that offer new ways of doing things, driven by consumers’ demands for a more digital, personalized two-way interaction. As these technology imperatives become mainstream, insurers must take the necessary steps to implement a digital-first strategy to orchestrate conversations more effectively across all parties related to the policy.

Most significant will be the continued adoption of modern communications tools and platforms whose growth was fast-tracked because of the pandemic – think on-demand movies streamed via mobile or advanced video communications platforms like Zoom, where daily downloads have increased 30x to provide opportunities for online interactions. That alone is not enough. The digital age is accelerating at an even faster pace for the insurance industry, which now faces more urgency than ever to transform operations to be more nimble and agile. This requires an insurer to act with determination and speed in their adoption of a digital-first platform.

Insurance Industry Responding to New Demands

Insurance organizations have aspired to build truly digital-first businesses over the last several years, however most had not achieved this pre-COVID. Today, the “nice-to-have” imperative is no more, with a true ultimatum in place to shift priorities and focus aggressively on this new paradigm. The pandemic has brought a seismic shift in the way consumers expect insurers to be digitally available and to respond to their preferences or jeopardize their relationship.

Nearly 40% of consumers in the U.S. indicated they changed their preference from direct mail to digital communications due to factors related to the COVID-19 pandemic.

To survive, insurers must accelerate their digital-first approach, which includes modernizing communication platforms. A large percentage of existing insurers are still running legacy Customer Communications Management (CCM) platforms, which impedes their ability to respond to the real-time expectations of policyholders and claimants.

Insurers can build the foundational components of a digital-first strategy by changing their approach to communications including:

STEP 1: Customer Conversations Roadmaps

Create customer roadmaps that define all the communications intersection points and opportunities, as well as customer preferences throughout the claims process.

STEP 2: Modern Customer Conversations Platform

Embrace a modern, cloud-based SaaS Customer Conversations Platform to provide digital-first, automated solutions like chatbots, self-service portals and mobile apps – providing new communications channels to engage customers in meaningful two-way conversations.

STEP 3: Cloud-First Adoption

Future-proof your strategy. Provide the scale, agility, multichannel communications, seamless integration, responsiveness and speed to market by embracing a modern conversations platform purposefully built for the cloud.

STEP 4: Enjoy the Benefits

Achieve long-lasting benefits of modernizing your communications platform as a top priority within your digital-first strategy, maximizing your ability to exceed customer expectations today and into the future, while also reducing costs.

The outcome of the pandemics presents insurance organizations the opportunity to learn from the past, by adopting the newer technologies that have proven their worth in the marketplace. Doing so will enable insurers to build a solid foundation for their digital transformation strategy, making it easier to meet consumer expectations, provide long-term value and carve out new competitive advantages.

Ready to apply these lessons learned to insurance? Contact us today to learn more about how your peers used the experiences from the pandemic to provide SMARTER conversations.

Smart Communications has long been recognized by all major analysts (Gartner, Forrester, Novarica and IDC ) as a Leader & Innovator in enterprise-scale Workflow & Content Automation (WCA) & Customer Communications Management (CCM) – and most recently by Aspire in its 2021 Leaderboard Assessment,  based on our proven cloud approach, our strategy for enabling meaningful two-way customer conversations and our platform that’s purpose-built for a post-pandemic customer experience.

Digitizing the RLS Application Process: How UK Banks Can Transform and Win New Business

 For banks in the UK, the Recovery Loan Scheme (RLS) presents a great opportunity to help business clients stay solvent during difficult times. The challenge? How to make it faster and easier for clients to apply for and gain approval to access these RLS funds within regulatory guidelines– without using traditional paper and face-to-face channels of communications. By implementing a digital Recovery Loan Scheme application strategy, the reward could be signing new clients and expanding existing relationships.

The answer is similar to what we’ve found with many banks in the U.S. It starts with replacing paper and PDF application forms with rules-driven digital interviews, which enable borrowers to engage over mobile, as well as desktop channels, upload supporting documents easily and automate complex calculations to reduce errors.

Creating Unforgettable Customer Experiences Through a Digital RLS Application Strategy and Maximize Opportunity

The British government launched the Recovery Loan Scheme in April 2021 to help businesses across the nation recover from financial struggles due to the pandemic. Businesses can apply for up to £10 million in government-backed loans through a variety of banks and lenders. RLS financing can be taken as a term loan, overdraft, invoice finance or asset finance.

Like the U.S. Paycheck Protection Program (PPP), the Recovery Loan Scheme has been incredibly popular, and it’s not difficult to understand why. Many businesses that were financially sound before the pandemic found themselves at the mercy of converging market forces that hit specific industries, like retail, hospitality and travel in unique and punishing ways.

However, like in the U.S., banks and lenders were left to figure out – in a hurry – how to manage the influx of applications and complex eligibility rules. This has resulted in a patchwork of processes that can vary wildly from lender to lender, leaving business owners in a state of confusion as to how they can take advantage of the RLS.

Commercial banking success depends on the ability to lend money quickly and make it easy for busy business banking customers to get the funds they need. While it sounds simple, this is easier said than done. To scale, lenders need to do three things well: digitize, simplify and automate as much of the RLS customer experience as possible.

Common Recovery Loan Scheme Friction Points Impacting the Customer Experience

A few common roadblocks make achieving that trifecta of customer bliss a challenge:

  • The need to complete, print and sign forms and physical documents create a burden on borrowers who may not be able to visit a branch
  • Borrowers are often confused about what sections of a form they need to complete, but using dynamic rules to guide them helps reduce abandonment rates
  • Handwritten forms require manual processing and often have errors that need resolution, slowing down the turnaround time
  • Forcing borrowers to speak to a loan officer on the phone to complete an application creates frustrations and time delays and puts lenders at a competitive disadvantage to those who offer easy digital application experiences
  • Basic digital forms that don’t allow a borrower to save progress mid-completion or allow switching between devices can further frustrate applicants


PPP Lessons for UK Banks: Winning Customers for Life

UK banks and lenders looking to differentiate themselves in the crowded RLS marketplace would be wise to apply some of the key lessons learned from the U.S. PPP. Smart Communications helped a number of banks accelerate their PPP Loan Forgiveness process with SmartIQTM, a low-code, drag-and-drop platform for forms transformation designed with speed and scale in mind.

Here’s an example of one lender’s situation before and after implementing SmartIQ:

Before:

  • When the PPP was introduced, the bank was inundated with requests, which was complicated by the inability to meet customers in person due to COVID-19
  • They had more than 650 loans to process, which would have taken half a dozen dedicated resources weeks to get through
  • The bank’s 11-page application was challenging for customers to navigate, causing further delays and support requests


After:

  • Entire loans can now be processed in a day or less
  • They attracted new customers away from banks who were too slow to meet the needs of PPP borrowers desperate for quick funds
  • Empowered applicants easily completed their forms with a guided digital interview experience that worked well across devices, resulting in increased customer loyalty (and public praise on social media)


Optimizing the Digital Recovery Loan Scheme Application Process

For time-sensitive market opportunities like the Recovery Loan Scheme, banks need to be agile and ready to deploy new forms in a hurry. Digitizing, simplifying and automating is more than just smart business, it’s an economy-saving effort. Enabling business owners to quickly and easily complete the Recovery Loan Scheme application could mean the difference between staff being made or redundant or meeting payroll. UK banks have a tremendous opportunity to build lasting relationships with customers by supporting them in these difficult times. With SMART technology in place, it’s never been easier.

Watch a short video demo of the SBA Paycheck Protection Loan Forgiveness Solution here.

For Insurers, Ad Hoc Doesn’t Have to Be Difficult

Cell phones and claims correspondence


By: Ruth Fisk, VP of Industry Marketing, Insurance at Smart Communications

Today, most of us carry more computing power in the palm of our hands than all of NASA had back in 1969 when it sent two astronauts to the moon, and yet despite this, most insurers are still saddled with labor-intensive, manual processes to create ad hoc claims correspondence experiences.

The number of smartphone users in the world today is 3.8 billion

Modernization in insurance is slow and difficult, with many systems that must be updated in order to truly deliver on the experiences that we as always-on, real-time consumers expect in every interaction.  While many insurers have done their best to build digital façades in order to appear to be a digital-first organization for their claimants, behind the scenes, many of their processes – including the creation of claims correspondence – is still riddled with age-old structured and methodologies.

Years ago, to describe claims communications the industry coined the term “ad hoc correspondence.” By definition, ad hoc loosely describes the significant number of one-off pieces of correspondence that may be created in claims operations on any given day.

However, claims professionals would likely agree that the synonyms that explicitly describe ad hoc are even more fitting:

impromptu · improvised · rough and ready · makeshift · make-do · cobbled together · thrown together · jury-rigged · quick and dirty · as the need arises · when necessary · when needed

Still prevalent today are legacy communication tools that leverage manually created, word-based or other outdated word processing tool templates, stored in individual files or on network shares to accomplish their “ad hoc correspondence” needs.  Claims professionals have become so accustomed to – and quite frankly don’t even think twice – about using this approach because it gives them the freedom to “roll their own” ad hoc letters.  However, these outdated tools expose a claims organization to higher operational costs and increased liability exposure for noncompliance:

  • Content control within templates is critical as the wrong message can create significant risks to the insured.
  • Redundancy in template content often makes the selection of proper templates overwhelming and increases the costs of maintenance and control.
  • Claims correspondence is always created because of some adjudication activity that occurs in the claims administration system, yet legacy solutions have limited integration capabilities available.
  • Claims administration systems lack the interactive correspondence capability which most carriers require.
  • Coordinating communication across all interested/active parties is arduous. Adjusters must prepare correspondence with the claimant, agent, third-party service providers, investigators, witnesses, medical providers and contractors.
  • Legacy communication tools do not provide the customer-centric approach required in today’s insurance environments, leaving claims professionals that create impersonal experiences for their customers.


The insurance industry is focused on delivering personalized digital experiences to improve its customer-centric approach.  However, archaic processes still exist in claims operations which make it difficult to manage the creation of real-time two-way conversational communications without the proper solutions. The ultimate interactive claims correspondence solutions, like our Conversation Cloud, achieve the perfect balance between a business user’s flexibility and critical organizational control and auditability.  Claims professionals will be asking why they didn’t make this change years ago!

With the proper tools – ad hoc doesn’t have to be difficult.

Modern conversation platforms provide interactive, real-time, two-way conversational capabilities that enrich the customer experience, enable faster claims resolution and ensure compliance – all while increasing the claim adjuster’s productivity and improving their job satisfaction. Migration tools are accessible to reduce the time required so you can retire those antiquated tools quickly.

What are you waiting for?  Start having SMARTER conversations today.

Smart Communications can help you with your digital journey.  We’ve long been recognized by all major analysts (Gartner, Forrester , Aspire and IDC ) as a Leader & Innovator in enterprise-scale Workflow & Content Automation (WCA) & Customer Communications Management (CCM) – including Aspire’s 2021 assessment which rates Smart Communications the #1 leader in the industry.

Contact us to learn more! 

Survey Recap: How Leading Insurers Can Build Trust

Mature couple using a laptop while relaxing at home, rebuilding trust in insurance


By: Neil Greathead, Chief Customer Officer at Smart Communications

The year 2020 was a difficult one for nearly all industries, and the insurance industry was no exception. Customers are now more accustomed than ever to digital-first interactions, and their expectations are at an all-time high. As we enter a post-pandemic world, insurers can build trust by rethinking customer engagement and how they can better meet customer needs.

Data gathered by Insurance Innovators, in partnership with Smart Communications and Salesforce Industries, provides valuable insights into how to improve trust and customer satisfaction. The main takeaway? It’s time to invest in SMARTER digital conversation capabilities that enable insurance companies to deliver targeted advice when and where it’s needed, ultimately recasting themselves as trusted advisors.

In this post, we recap key findings from the research. Read more below or check out the full research report and infographic.

Getting Clear on Better Customer Conversations

The research found that 84% of insurance executives are already bought in on the idea that better customer communications can reverse the trend of eroding trust. They also seem clear on where the challenge lies: 90% believe that when customers find descriptions of product features and add-on products confusing at the point of sale, it makes them more distrustful of insurers. Webpages with too many coverage options overwhelm customers, especially when what they see isn’t relevant to their situation. Respondents agree that personalizing plan options and documents using data and analytics would have a massive impact in minimizing loss of trust.

According to the survey, greater clarity and personalization helps build trust both at the point of sale and when claims are filed. 78% of respondents believe that poor customer understanding of coverage greatly undermined trust when claims proved contentious during the pandemic. Yet insurance leaders also recognized the opportunity this represents: 69% believe trust can be protected by using data analysis to anticipate confusing policy terms and tailor messaging accordingly.

Improving Digital Experiences to Meet Rising Expectations

Insurers build trust by managing customer expectations during the claims process. 89% of those surveyed cited delays as the biggest factor that dented trust during the pandemic. Customers experiencing upheaval in their personal or business finances did not have patience for opaque, slow turnaround times. Again, this challenge points the way to an opportunity: 81% believe that real-time digital updates would safeguard trust.

Ultimately, insurance leaders agree that without a seamless digital experience, the ability of insurers to build trust will continue to suffer. Consumers know what better looks like when it comes to digital experiences, and companies who don’t invest in improving customer communications will be left behind. 

The New Recipe for Success: Personalization, Seamless Omnichannel Experiences, and Self-Service Automation

Despite all the challenges the survey touched on, it’s not all doom and gloom. We also uncovered practical tips for how smart insurers can reverse the tide of declining trust to win customers for life. The three-part recipe for success? Personalization, a seamless omnichannel experience, and easy and fulfilling self-service automation.

Personalization

Insurance executives believe it’s time to get personal. An overwhelming 98% said optimizing personalized customer contact in all digital interactions would increase trust. Personalization conveys both relevance and empathy. Customers want to be known and understood by the companies they work with. They’ve been trained by Amazon’s algorithms to receive highly relevant product recommendations and want that same kind of insightfulness across all their digital interactions. This doesn’t simply result in higher sales. Understanding implies caring. When customers feel heard and understood, it quickly translates to positive brand associations.

Omnichannel Experiences

Second, respondents unanimously recognize that customers want an incredible experience no matter what device or platform they happen to be on at the time. 95% agree that frictionless experiences are crucial to insurance building trust, while frustrating digital interactions have a negative impact. In a world where customers rapidly cycle through their devices, and data automatically syncs between them, they expect their insurers to follow suit.

While insurers might feel the pinch of managing communications across so many different digital platforms simultaneously, customers don’t have such a nuanced view. If a customer first engages with online chat, they expect all that information to carry through on any device or platform – regardless of where their next interaction is. Insurers have a major opportunity to invest in technology platforms, such as Smart’s Conversation Cloud that enable this seamless omnichannel experience for every customer, every time.

Self-service automation

Third, customers are clamoring for more and better self-service tools. Consumers don’t mind helping themselves. In fact, some even prefer digital over human interactions. There are several proactive self-service automation strategies insurers can employ to increase trust, according to respondents:

  • Pre-populate forms with as much of the data as you already have
  • Introduce advanced virtual agents that can actually help a customer resolve an issue from start to finish
  • Use AI chatbots to provide proactive guidance where needed


A New Relationship Norm: Insurers Build Trust as Advisors to Customers

For insurers, the end goal of digital transformation is to redefine the relationship they have with their customers. Instead of being viewed as a business you only communicate with when there’s a problem, insurers have a significant opportunity to flip the script and upgrade the value they provide customers. The research indicated that 94% of insurance executives believe that offering personalized advice to reduce risk will eventually become the core insurance company value proposition. Instead of waiting until disaster strikes and helping to pick up the pieces, insurers can instead become known for helping customers avoid disaster in the first place.

How can insurers make this shift? By avoiding cookie-cutter communications. Among those surveyed, 90% warn that unless a touchpoint is personalized, frictionless, and adds value, it will only irritate customers. Conversely, by leveraging SMART technology that provides customized, convenient, and value-added conversations, insurers can win the hearts and minds of their customers.

Ultimately, COVID-19 exposed the gap between what insurance customers expect and their actual experience. With the pain points now clearly revealed, they can be solved. Adding value to a customer’s daily life through enhanced digital communications is the path forward.

Want to learn more about how insurers can increase trust more than ever? Download the full Rebuilding Trust in Insurance infographic or read the full results.